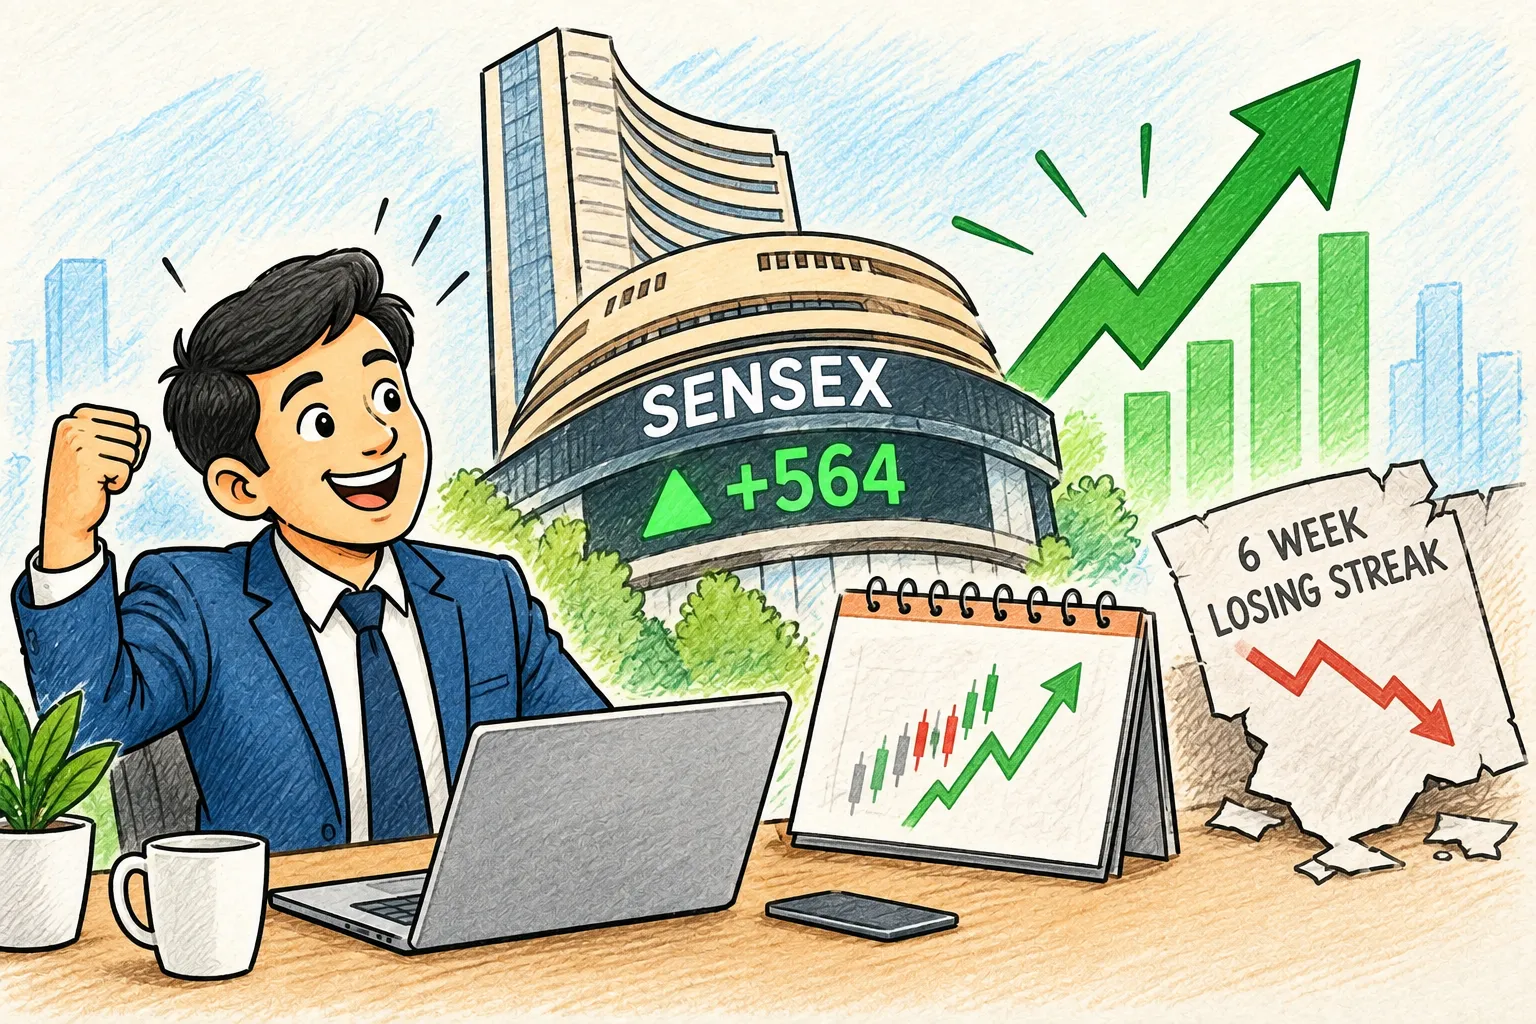
The Sensex gained 564.03 points to close at 74,858.99 on September 21, ending a six week losing streak, its longest in about six years, as falling crude oil prices and softer US bond yields lifted sentiment.
Benchmarks Snap Their Longest Losing Run in Years
Indian equity benchmarks rebounded on September 21, 2026, with the BSE Sensex climbing 564.03 points, or 0.76 percent, to close at 74,858.99. The NSE Nifty 50 rose 67.90 points, or 0.29 percent, to settle at 23,414.30. The gains brought to an end six consecutive weeks of losses for both indices, described by several market commentators as their longest weekly losing streak in roughly six years.
Reuters noted that most major sectors advanced during the session, led by heavyweight movers including HDFC Bank, ICICI Bank and Reliance Industries, whose combined weight in the benchmark indices helped drive the headline gains. Smaller companies lagged behind, with the Nifty Smallcap 100 slipping about 0.1 percent and the Nifty Midcap 100 falling roughly 0.3 percent, a divergence that shows the rebound was concentrated in large caps rather than broad based.
What Drove the Turnaround
Falling crude oil prices were among the biggest positives for Indian equities during the session. Brent crude extended its losing streak to four sessions, sliding more than 3 percent on September 21 to around 101.20 dollars a barrel, as expectations grew that Saudi Arabia could restore oil shipments even though continued Houthi attacks and stalled US-Iran talks kept supply concerns in focus. A sustained decline in crude prices matters for India because it can ease pressure on the country's import bill, inflation trajectory and current account position, and can also reduce pressure on the rupee.
US Treasury yields also moved lower after a recent sharp rise had pushed them above the psychologically important 5 percent mark. The 10-year US Treasury yield fell to 4.95 percent during the session, while the 30-year yield declined to 5.28 percent. Lower bond yields tend to support equities by reducing the relative attractiveness of fixed income assets.
Institutional Flows Turned Supportive
Foreign institutional investors purchased approximately Rs 599.54 crore worth of Indian equities in the previous session, ending a seven session selling streak that had weighed on sentiment through much of the month. Domestic institutional investors remained supportive as well, buying more than Rs 1,000 crore worth of shares in the prior session, providing an additional cushion even as foreign flows had been volatile through September.
| Metric | Value on September 21, 2026 |
| Sensex close | 74,858.99, up 564.03 points |
| Nifty 50 close | 23,414.30, up 67.90 points |
| Brent crude | Around 101.20 dollars a barrel |
| US 10-year Treasury yield | 4.95 percent |
| FII equity purchases (prior session) | About Rs 599.54 crore |
A Modest Bounce, Not a Reversal of the Trend
Despite the day's gains, overall market capitalisation of Indian equities actually fell by about Rs 8,516 crore during the session, to Rs 481.52 lakh crore, as losses in the broader market outweighed gains concentrated in benchmark heavyweight stocks. Market breadth stayed weak through the session, another sign the rally was narrower than the headline index numbers suggested.
The rebound also coincided with the closing days of the National Stock Exchange's own Rs 22,562 crore initial public offering, one of the largest share sales in Indian history, which can temporarily divert liquidity away from existing listed shares as investors set aside cash for new allocations. That effect tends to show up first in small and midcap indices, which depend more heavily on steady retail participation than the large cap dominated benchmarks do.
Also Read: EPFO Wage Ceiling Raised to Rs 25,000, Effective September 17
What to Watch Next
Market participants will be watching whether the recovery broadens beyond a handful of large cap names once the NSE IPO related liquidity effects pass, and whether crude oil prices continue easing or reverse course given the ongoing tensions in West Asia. Crude remaining above 100 dollars a barrel, elevated global interest rate concerns, and the still uncertain direction of foreign investor sentiment all remain live factors.
For now, the session offered some relief to investors after a difficult stretch, but a single day of gains, however sharp relative to recent weeks, does not on its own confirm that the broader six week downtrend has been reversed.