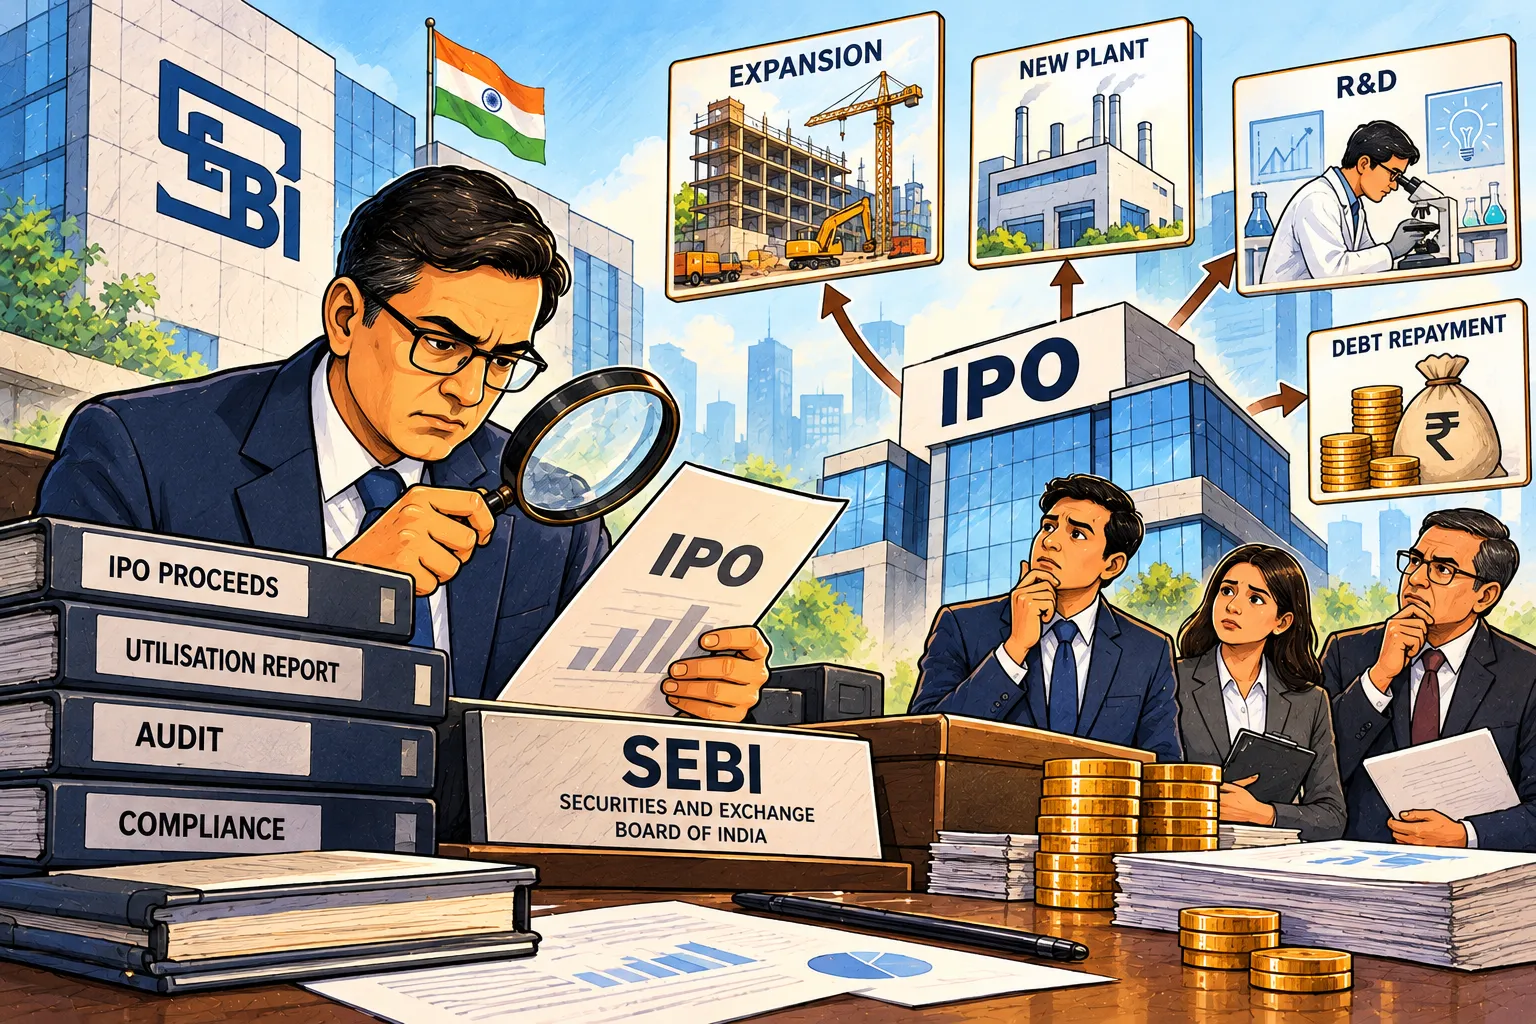
SEBI, India’s market regulator, has proposed that every public issue get a monitoring agency to check how companies spend the money. Firms that refuse to cooperate could face fines and frozen promoter demat accounts.
SEBI Opens a Paper on IPO Money Tracking
On Tuesday, October 13, 2026, the Securities and Exchange Board of India (SEBI) issued a consultation paper. A consultation paper is a draft idea that SEBI shares to get public feedback. It is not a final rule.
The paper covers how listed companies use money raised from the public. It follows recommendations from a working group that reviews SEBI’s Listing Obligations and Disclosure Requirements (LODR) rules. V S Sundaresan, a former SEBI executive director, chairs that group.
The paper covers only one chapter of the group’s work. The group has also sent reports on related-party deals and on penalties that stock exchanges can levy.
What Does a Monitoring Agency Check?
A monitoring agency is an independent body that checks whether a company spent its issue money on the goals it told investors about. Those goals can include building plants, paying off debt or funding daily operations.
It checks how the issue money was used against the plan in the offer document. It reviews the company’s disclosures and spending records, and it reports whether the money went where it was meant to go.
Every Public Issue Would Need a Monitoring Agency
The working group wants an agency for every issue, no matter how large. The offer for sale part would stay outside this rule.
Agencies would also report straight to the stock exchanges. Exchanges would show those reports, and any note of non-cooperation, in a clear place on their websites.
Why the Offer for Sale Part is Left Out
An offer for sale is when existing shareholders sell their shares. That money goes to the sellers, not to the company. So there are no company funds to track for that part. The rule would count only the fresh issue money.
What Happens if a Company Does Not Cooperate?
If a company does not cooperate, the agency would still file a report. It would use the best information it has and add a statement of non-cooperation. Then a series of steps could follow:
- Fine: an exchange may charge ₹50,000 for each instance of non-cooperation reported in a quarter or half-year. It would send notices within 30 days of the report’s due date.
- Notice to promoters: the full report may still be missing, or the fine unpaid, 15 days after the notice. Then the exchange would send notices to promoters.
- Demat freeze: if the default lasts 10 days after that, the exchange would ask depositories to start freezing the promoters’ demat accounts.
A demat account is where a person holds shares in electronic form. A freeze stops the holder from selling or moving those shares.
Fees and Other Rules in the Paper
Not paying the agency’s fee would not count as non-cooperation. Instead, agencies could ask for the full fee in advance. They would refund the unused part if the deal ends before the money is fully spent.
If a company fixes its default, the agency must file a complete report within 15 days of getting the information. The report must say the default has been fixed.
A company that is reported for non-cooperation could not end its deal with the agency. It also could not hire a new one until it fixes the default and allows a complete report for that quarter.
Reporting deadlines for agencies would also move from one rulebook to another. They would shift from the Issue of Capital and Disclosure Requirements (ICDR) rules into the LODR rules, so the rules line up.
What Counts as Non-Cooperation
A report on the paper says non-cooperation could include failing to give needed information, delaying documents or blocking the agency from finishing its report. As noted, unpaid agency fees would not count.
Under the current rules, not every monitoring report has to be made public. The new plan would put the reports and any non-cooperation notes on exchange websites.
Freezing Promoter Accounts is Not New
SEBI already uses a fine-then-freeze approach for some LODR breaches. A 2016 SEBI circular told exchanges to freeze promoter holdings when a listed company fails to pay fines for certain breaches. The new paper builds on that idea for issue-money reports.
News reports in May 2026 had described earlier draft ideas from the group. One idea was to lower the size at which an agency becomes mandatory, from ₹100 crore to ₹50 crore. The October paper goes further and drops the size test.
A Separate IPO Relief on the Same Day
SEBI also made a separate IPO move on October 13. It extended until March 31, 2027 a relief that lets IPO-bound companies change their fresh issue size by up to 50 per cent. They need not file fresh draft papers for this, if the main goal of the issue stays the same. The lead manager must justify the change.
The earlier relief expired on September 30. SEBI had first given it because of the West Asia war. It applies to issues that open on or before March 31, 2027. Merchant bankers must also tell the public about the changes through an addendum.
Also Read: UPI MDR is Delayed Until After Diwali: Who Will Pay the Fee When It Starts?
Are the SEBI Proposals Final?
No. They are consultation proposals. SEBI has asked for comments and the reasons behind them by November 3, 2026. Final rules, if any, would come only after SEBI reviews that feedback. That makes November 3 the key date for anyone who wants to respond.
How People Can Send Comments
SEBI has asked for views from the public and other stakeholders. People can send comments and suggestions along with their reasons through the link on SEBI’s website.