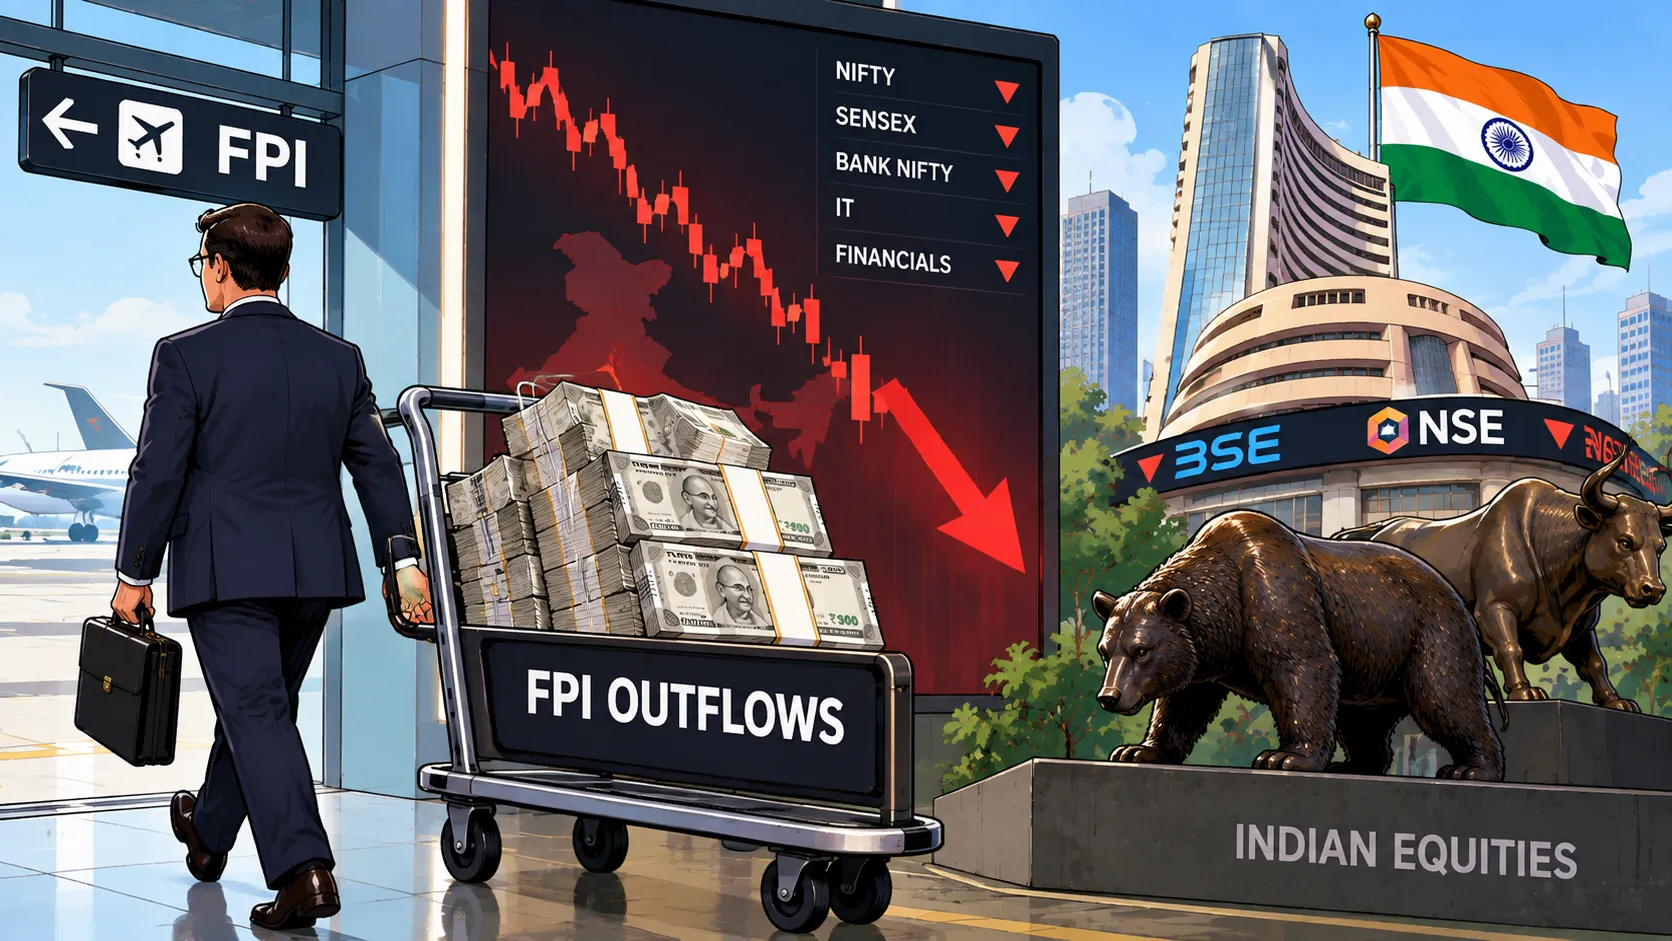
Foreign portfolio investors have withdrawn ₹20,974 crore from Indian equities so far in September, taking 2026's total equity outflow to ₹2.45 trillion, already larger than the whole of 2025, according to depository data.
A Two-Month Return, Then a Reversal
Foreign portfolio investors had come back to Indian equities over the previous two months before turning sellers again in September. CDSL data puts the September outflow at ₹20,974 crore up to September 18. That follows net purchases in July and August, which makes the current month a break in a short recovery rather than the continuation of a steady exit.
The calendar-year picture is heavier. FPI equity flows in 2026 look like this:
- July 2026: net inflow of ₹20,200 crore
- August 2026: net inflow of ₹29,630 crore
- September 2026, to September 18: net outflow of ₹20,974 crore
- Calendar 2026 so far: net outflow of ₹2.45 trillion
- Calendar 2025, full year: net outflow of ₹1.66 trillion
In other words, foreign investors have already pulled more out of Indian equities in under nine months of 2026 than they did across all of 2025.
The Three Pressures Market Participants Are Citing
Dheeraj Gaur, chief investment strategy officer at Choice Wealth, attributed the September selling to three factors: higher US interest rates and bond yields, elevated crude oil prices amid geopolitical tension, and weakness in the Indian rupee. The US Federal Reserve has raised rates to 3.75 to 4.00 per cent, and a narrower yield gap between India and the United States reduces the relative pull of Indian assets.
V K Vijayakumar, chief investment strategist at Geojit Investments, said elevated crude prices and a US 10-year yield around 5 per cent are negatives for Indian equities and for foreign flows, while a resilient domestic economy and expectations of better earnings growth work in the other direction. Vedant Gupte of Trackk described the month's selling as a crude and dollar story rather than an India-specific one, on the view that money leaves emerging markets broadly when oil spikes and US yields firm up.
Both framings matter for reading the number. A withdrawal driven by global rates and oil is a different signal from one driven by concerns specific to Indian company earnings or valuations.
Debt Markets Saw Withdrawals Too
The selling was not confined to equities. During the period under review, foreign investors withdrew ₹10,296 crore through the Fully Accessible Route, ₹1,817 crore via the Voluntary Retention Route and ₹1,068 crore through the general route.
The Fully Accessible Route allows unrestricted foreign investment in specified government securities, and it has been the main channel for index-linked flows into Indian government bonds. Outflows there alongside equity selling point to a broader repricing of Indian assets by foreign investors this month rather than a rotation from one asset class into the other.
The Primary Market Held Up
One part of foreign activity stayed positive through September. FPI investment through the primary market continued during the month even as secondary-market selling picked up, which is consistent with a heavy initial public offering calendar drawing institutional participation.
That split is worth keeping in view. Headline FPI figures blend secondary-market trades with primary-market subscriptions, so a single negative number can understate foreign appetite for new paper.
Regulatory Easing in the Background
Foreign investors have also had a slightly lighter compliance load this month. On September 7, the Securities and Exchange Board of India eased requirements for FPIs investing only in government securities by removing the need for such investors to furnish investor-group details. The change took effect immediately and followed earlier changes introduced by the Reserve Bank of India in June.
Separately, the government has previously framed foreign outflows as part of a wider emerging-market pattern. In a written reply in the Lok Sabha on July 27, Minister of State for Finance Pankaj Chaudhary said the outflows from Indian equities were part of a broader pattern in emerging markets and not altogether specific to India.
Also Read: Tata Sons Row Deepens as Trusts Declare Chairman Vote Void
What Indian Investors Can Read Into the Number
FPI flows are a monthly signal, not a verdict. The figures show that foreign selling in September has been large enough to erase a good part of the July and August inflows, and that the drivers being cited are largely external: US rates, crude, and the rupee. Going forward, market participants quoted in the data release expect flows to track the Iran and US conflict and its effect on crude prices.
For anyone following domestic equities, the practical point is that the direction of these flows over the coming weeks is likely to be decided outside India, which makes oil prices and US yields worth watching alongside company results.