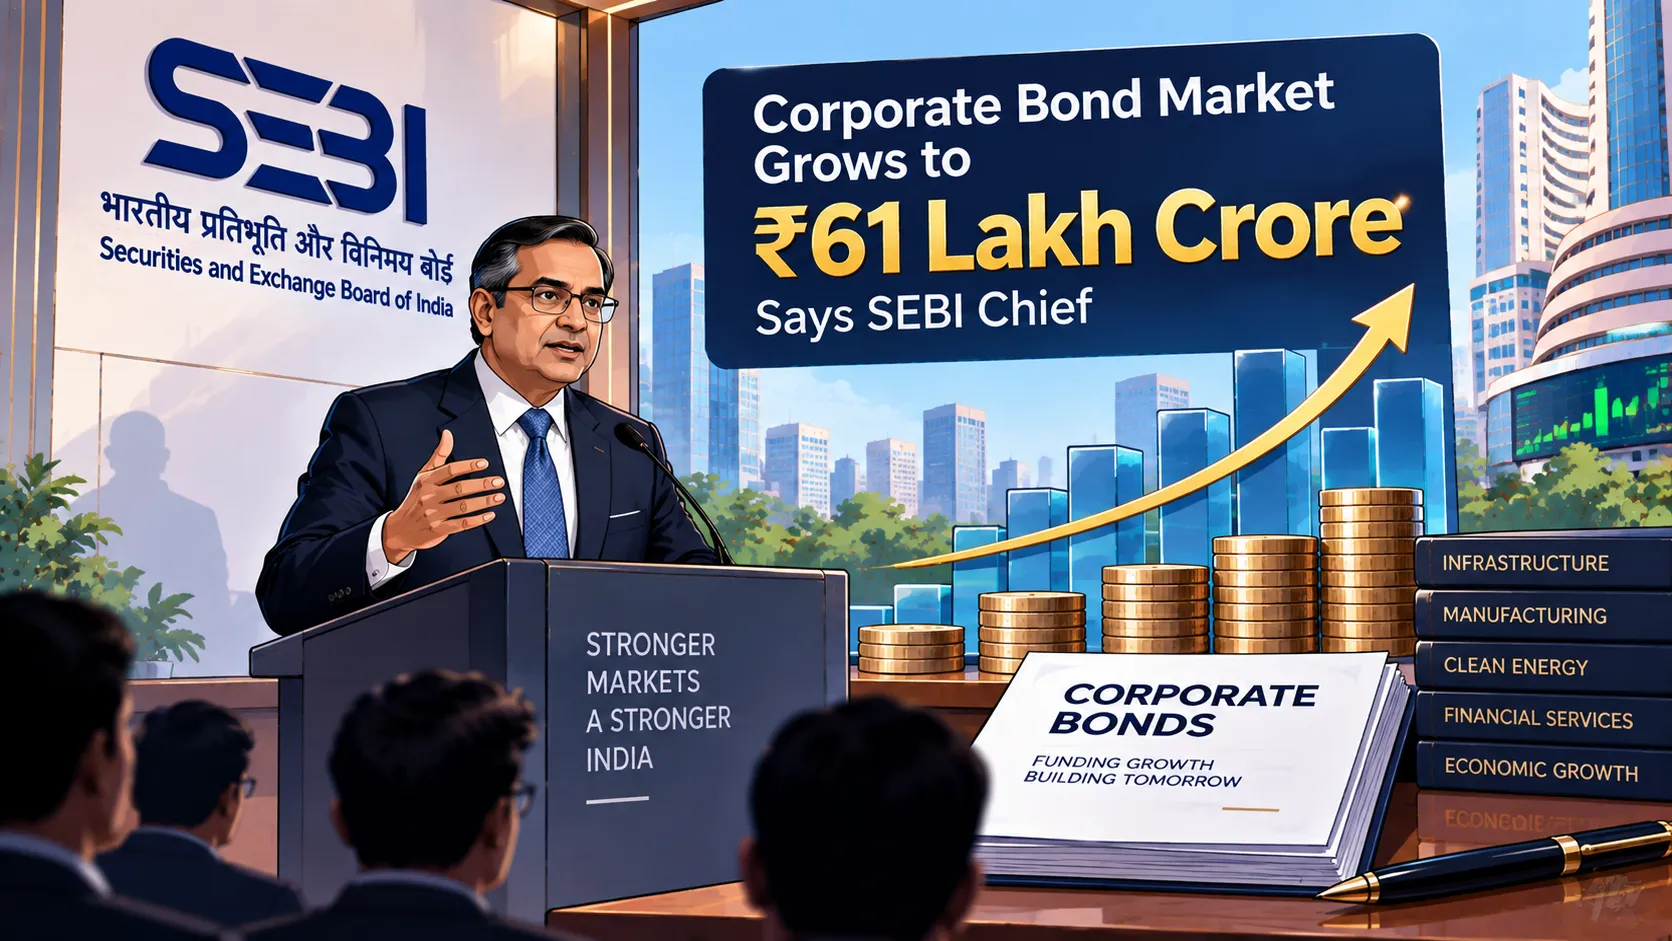
India's outstanding corporate bond market has grown to about Rs 61 lakh crore from Rs 20 lakh crore in FY2015-16, SEBI Chairman Tuhin Kanta Pandey said on September 22, adding that more than Rs 4.3 lakh crore has already been raised through corporate bonds this financial year.
What the SEBI Chairman Said
Addressing the 11th J.P. Morgan India Conference on September 22, 2026, SEBI Chairman Tuhin Kanta Pandey said India's corporate bond market has expanded roughly threefold over the past decade, growing from around Rs 20 lakh crore in FY2015-16 to about Rs 61 lakh crore currently. He added that companies have already raised more than Rs 4.3 lakh crore through corporate bonds in the current financial year, FY2026-27, which began in April.
Pandey said SEBI's approach has been to develop the entire market ecosystem around corporate bonds rather than focus narrowly on increasing issuance volumes. According to him, building a genuinely deeper bond market requires more than higher issuance alone, since it also depends on a wider base of issuers, improved price discovery, broader investor participation and stronger liquidity in the secondary market.
Why Ecosystem Depth Matters More Than Volume
A bond market can grow in size purely through more companies issuing debt, while still remaining shallow in practice if very few investors actively trade those bonds once issued, if only a narrow set of large, well known companies can access the market, or if bond prices are difficult to determine because trading is infrequent. Pandey's framing suggests SEBI views the market's current growth as encouraging on the issuance side but still requiring further work on these other dimensions before it can be considered fully mature.
SEBI has pursued reforms across several parts of the corporate bond ecosystem in recent years, spanning how bonds are issued, how they are distributed to investors, the market infrastructure supporting trading and settlement, and efforts to improve investor understanding of bond products. The Rs 4.3 lakh crore raised so far in FY2026-27 indicates the pace of issuance has remained strong even as the regulator continues layering in these structural reforms.
| Metric | Figure |
| Outstanding corporate bonds, FY2015-16 | About Rs 20 lakh crore |
| Outstanding corporate bonds, current | About Rs 61 lakh crore |
| Raised via corporate bonds in FY2026-27 so far | More than Rs 4.3 lakh crore |
| Growth over roughly a decade | Around threefold |
A Pilot for the Market's Next Phase
Pandey's remarks on ecosystem depth follow SEBI's launch of a pilot project called Demat 2.0 earlier this month, which tests the tokenisation of corporate bonds using distributed ledger technology. Under that pilot, three issuers, REC Limited, Larsen & Toubro and IIFL Finance, together raised Rs 1,025 crore through tokenised corporate bonds in early September, with the bonds linked to the Reserve Bank of India's wholesale central bank digital currency for settlement.
The pilot is designed to test whether recording bond ownership on a shared, permissioned digital ledger, rather than through a conventional database structure, can allow the securities and payment legs of a bond transaction to settle simultaneously, a mechanism known as atomic settlement. SEBI has described Demat 2.0 as a three stage rollout, with the current institutional issuance phase to be followed by secondary market trading and, eventually, retail investor access, meaning the initiative remains some distance from directly affecting individual retail bond investors for now.
Context for India's Broader Capital Markets Push
Pandey's comments on the bond market came alongside separate remarks in which he said India could potentially raise around Rs 2 lakh crore through IPOs in the current financial year, with about 55 percent of FY2026-27 proceeds so far representing fresh capital for issuing companies rather than existing shareholders selling stock. Taken together, the two sets of remarks point to a regulator emphasising growth across both the equity and debt sides of India's capital markets simultaneously.
For companies, a deeper and more liquid corporate bond market can mean easier access to debt financing at potentially better pricing, reducing reliance on bank loans alone. For investors such as mutual funds, insurers and pension funds, a market with better price discovery and stronger secondary market liquidity can make it easier to buy and later sell bond holdings without moving prices sharply against themselves.
Also Read: Tata Sons Board Votes to Comply With RBI Listing Direction
What to Watch Going Forward
The scale of India's corporate bond market growth over the past decade is substantial in absolute terms, but Pandey's own framing suggests SEBI does not consider the job finished. Investors and market participants should watch for further regulatory steps aimed specifically at secondary market liquidity and price discovery, alongside the progress of the Demat 2.0 tokenisation pilot as it moves toward its later, more market-facing phases.